ServicesUSDA Loans
USDA Loans in Manor, TX
A USDA guaranteed loan can finance the full purchase price with no down payment, as long as the address, your income and the property all pass. We check each of those before you shop, so a rule nobody mentioned doesn't stall your closing.
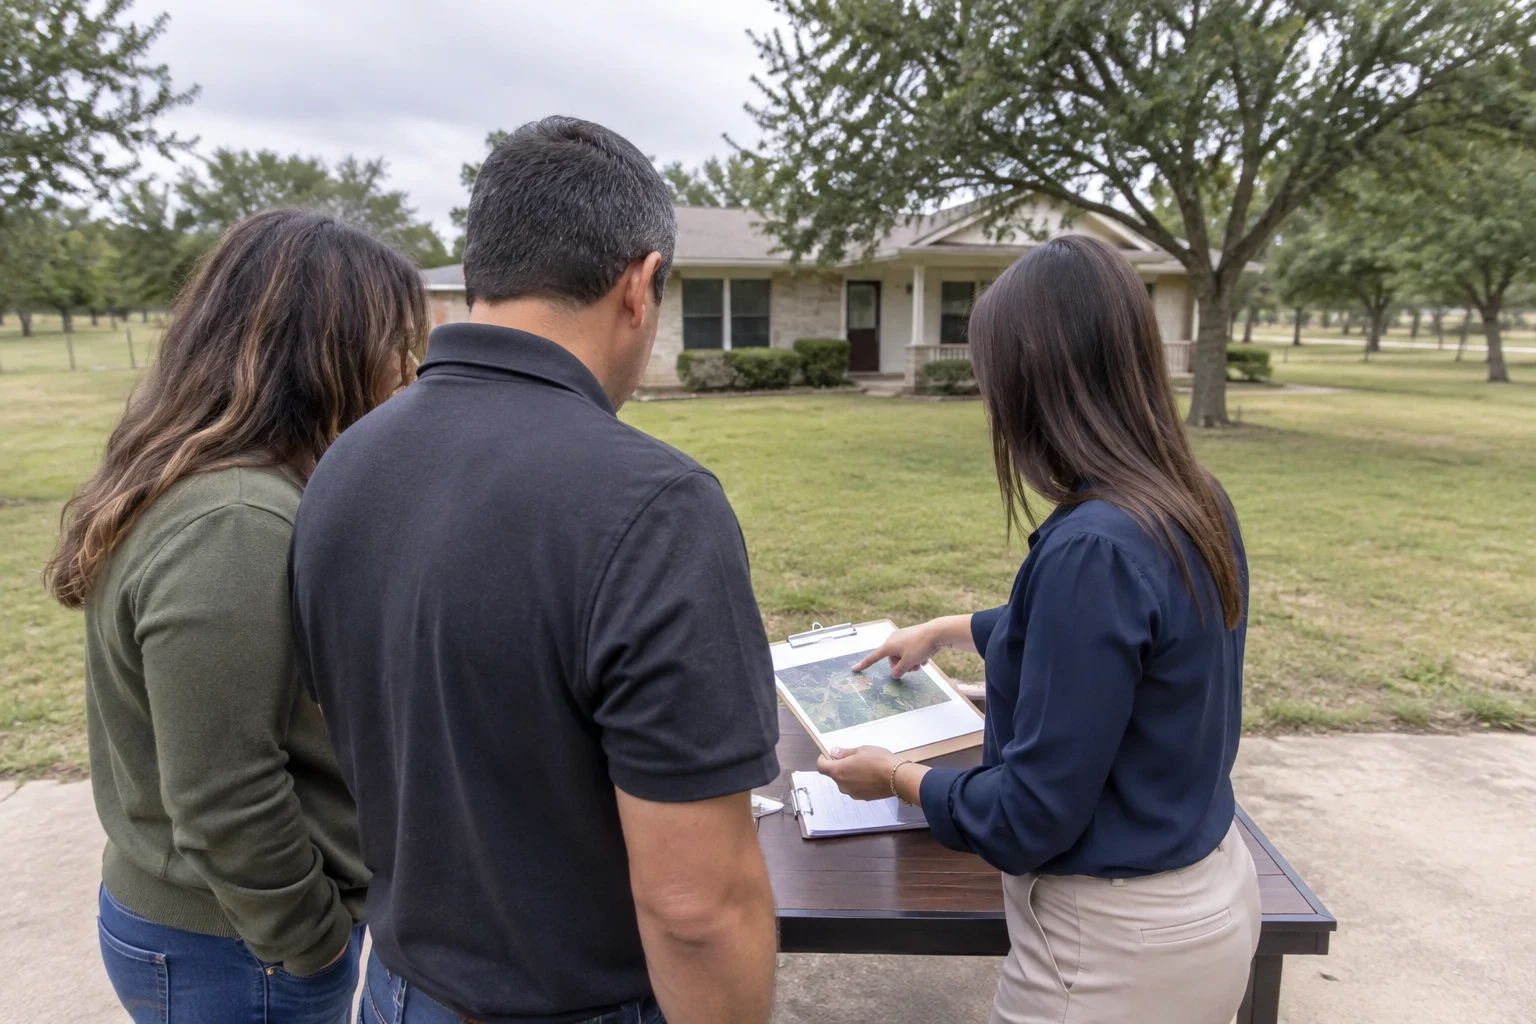
What a USDA Loan Is and Who It Fits
The USDA Single Family Housing Guaranteed Loan is a 30-year fixed-rate mortgage backed by the U.S. Department of Agriculture. Because the agency guarantees most of the loan, a lender can finance up to 100 percent of the appraised value. It is not a farm loan. It is built for buyers of modest means purchasing a primary residence in an area USDA classifies as rural.
Most USDA files that fall apart do so over a small detail checked too late: an address a few blocks outside the eligible boundary, income from a spouse that wasn't counted, or a septic system the appraiser flags. Our loan officers work through those details at the start, not in the final week.
If USDA turns out not to fit, we'll say so and explain why. FHA loans, VA loans and conventional loans may be the better route, and we compare them for you on the same call.
What We Handle on a USDA Loan
- Exact-address eligibility check
- We look up the specific property on the USDA eligibility map, not the general area. Boundary lines can split neighboring streets, so we confirm each address you're serious about before you write an offer.
- Income limit calculation
- USDA caps income at a percentage of the area median, and it counts every adult who will live in the property, not only the borrowers on the note. We run that total, then apply the allowed deductions for dependents and childcare.
- Credit and debt ratio review
- We pull credit and measure your housing payment and total debts against USDA ratio guidelines. If a score or balance is close to a limit, we show you which account to address first.
- GUS automated underwriting
- We run your file through USDA's Guaranteed Underwriting System and read the findings line by line. Any conditions it returns, we walk through with you by phone as a specific document list.
- Appraisal and property standards
- The property must be safe, sound and sanitary. We tell you ahead of time what an appraiser looks for, including well water tests and septic inspections on rural lots.
- USDA agency review
- After our underwriting approval, the file goes to USDA for its own review. We package it cleanly so it doesn't come back with avoidable questions.
Signs a USDA Loan May Be the Right Call
Savings are short of a down payment
You earn enough to carry a mortgage payment, but saving 3 to 20 percent of the price would take years. USDA removes the down payment requirement entirely.
You're looking outside the dense core
Areas around Manor, Elgin and Taylor include addresses that may sit inside USDA boundaries. We confirm the exact line.
Your income is moderate, not high
USDA is aimed at buyers under the area income limit. If your family income falls under it, this program often beats FHA on monthly mortgage insurance cost.
You plan to live in the property
USDA only finances a primary residence. If this is where you'll live, the program fits; if it's a rental, it doesn't.
You don't already own a suitable residence nearby
Borrowers generally can't own another adequate dwelling within commuting distance. First-time buyers usually clear this easily.
How a USDA Loan Moves From Call to Closing
- 1
Pre-qualification by phone
We talk through income, debts, credit and the areas you're considering. You'll know whether USDA is realistic and roughly what price range fits.
- 2
Address and income verification
We check the income limit against everyone living in the property and test each address you're watching on the eligibility map. This happens before you make offers, not after.
- 3
Application and underwriting
Once you're under contract, we take your full loan application, collect pay stubs, W-2s, tax returns and bank statements, and run the file through GUS. Our underwriter then clears each condition.
- 4
Appraisal and USDA review
The appraiser values the property and checks it against USDA standards. After our approval, USDA reviews the loan itself, which adds days to the timeline, so we build that into your closing date.
- 5
Closing
You sign at the title company, the guarantee fee is collected or financed, and you receive the keys. We review your final numbers with you before closing day.
What Moves the Cost of a USDA Loan
A USDA loan has no down payment, but it does carry fees, a rate and closing costs. The total depends on the property, your credit and how the deal is structured. We show every cost in writing so you can compare it against an FHA or conventional option.
- Guarantee fees
- USDA charges an upfront guarantee fee, which can be rolled into the loan, and a smaller annual fee paid monthly. These usually run lower than FHA mortgage insurance.
- Your credit profile
- Your score and payment history affect the rate you're offered and whether GUS returns an automated approval or sends the file to manual review.
- How closing costs are covered
- Closing costs can be paid in cash, covered by seller concessions, or partly financed when the appraisal comes in above the price. Each choice changes your loan amount and cash to close.
- Rural property items
- Well water testing, septic inspections and survey work on larger lots add to third-party costs. We flag them early so they aren't a surprise.
USDA Loan Questions We Hear Often
Something not covered here? (512) 271-4623
Is the house I want in Manor eligible for USDA?
It depends on the exact address. Some properties around Manor and the surrounding area fall inside USDA boundaries and some don't, and the line can change when the map is updated. Give us the address on a call and we'll check it directly.
Whose income counts toward the limit?
USDA looks at the income of every adult who will live in the property, even people who won't be on the loan. Allowed deductions, such as those for dependent children, can bring the total down. We calculate it carefully because this is where many applicants guess wrong.
What credit score do I need?
Many lenders look for around 640 to get an automated approval through GUS. Borrowers below that can sometimes qualify through manual underwriting with stronger compensating factors. We review your report and tell you where you stand.
Can I use a USDA loan on new construction?
Yes, a newly built property can qualify if it's in an eligible area and is complete with a certificate of occupancy before closing. We coordinate with the builder's timeline so the paperwork lines up.
Can I buy a rental or second residence with USDA?
No. The program only finances a primary residence you'll occupy. For investment purchases, hard money loans or conventional loans are the options we'd discuss instead.
Find Out if USDA Fits Before You Shop
A short call tells you whether your income and target areas line up with USDA, and what your pre-qualification looks like. We'll also compare it against FHA and conventional so you choose with the full picture.