ServicesBank Statement Loans
Bank Statement Loans in Manor, TX
Your tax return shows what is left after write-offs. A bank statement loan qualifies you on what actually lands in your accounts. We read your deposits line by line, separate real income from transfers, and build a file an underwriter can follow without guesswork.
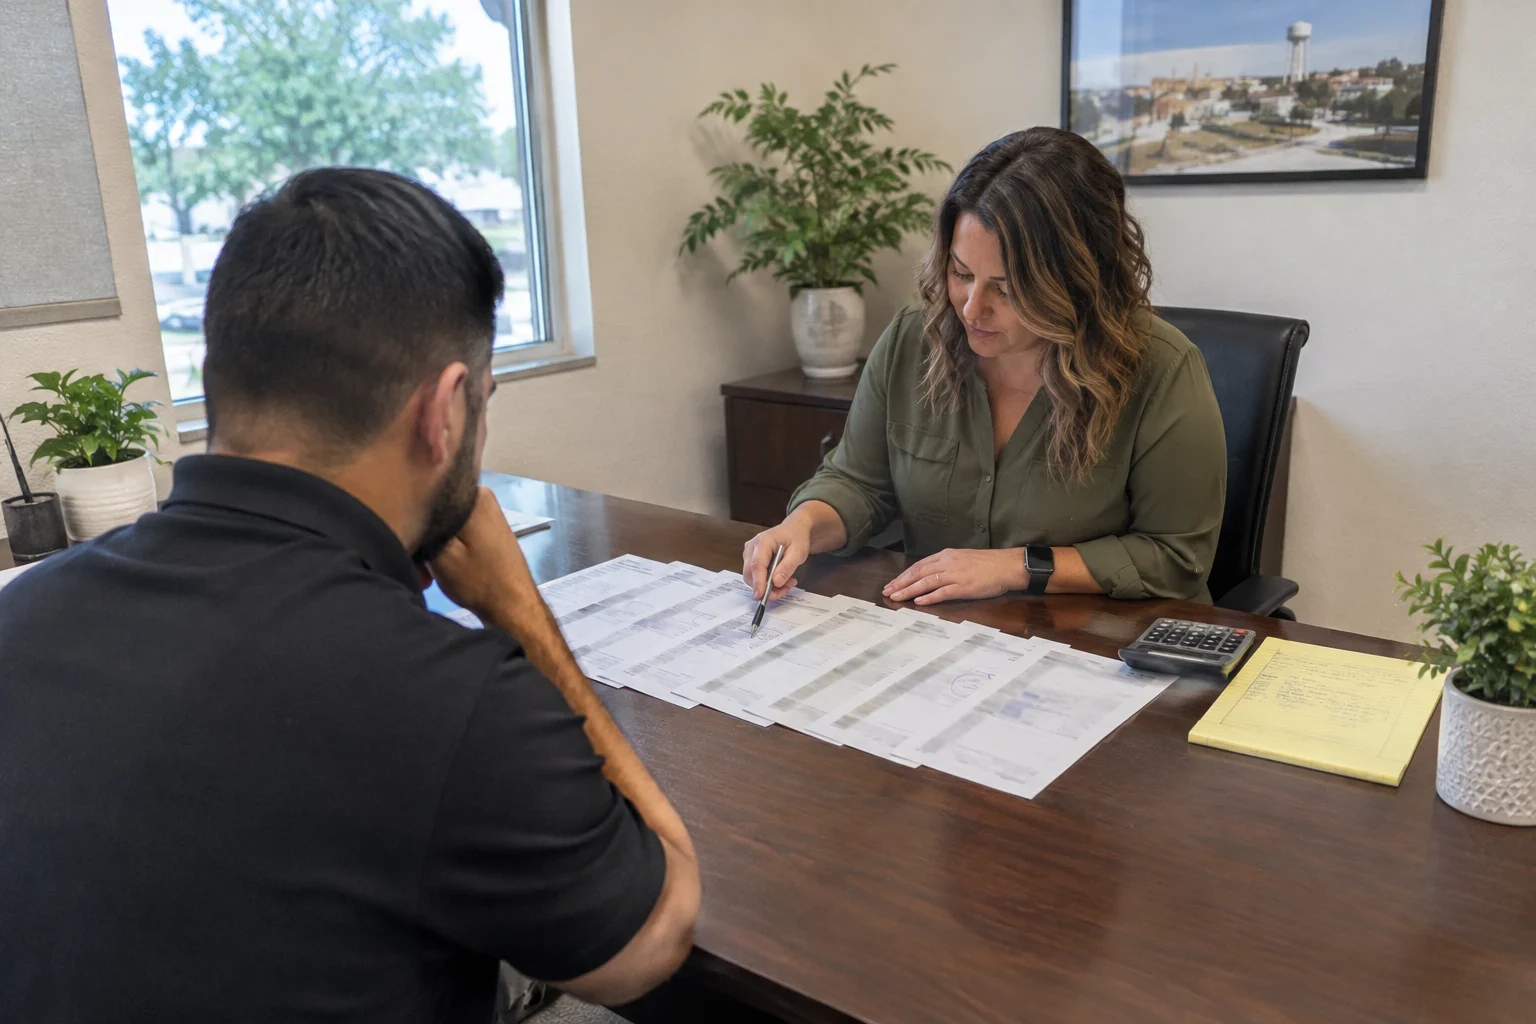
Income measured from deposits, not from Schedule C
A bank statement loan is a home loan for self-employed borrowers that replaces tax returns and W-2s with 12 or 24 months of bank statements. The lender totals your qualifying deposits, applies an expense factor to business accounts, and divides by the number of months to arrive at a monthly income figure. That figure, not your adjusted gross income, sets how much you can borrow.
It fits business owners, 1099 contractors and people who earn on commission, especially when depreciation, mileage and equipment write-offs make a good year look thin on paper. These programs sit outside conventional guidelines, so rates and down payment requirements usually run higher. If your returns already show enough income, we will tell you so and price a conventional loan instead.
Most of the work is in the details. A single unexplained transfer between your own accounts, counted as income, can get a file kicked back weeks into underwriting. We find those items before an underwriter does, which is what keeps a closing date where you set it.
What we do on a bank statement file
Deposit-by-deposit review
We go through every statement and mark each deposit as business revenue, a transfer between your own accounts, a refund, or a loan advance. Only true income counts, and we document why each excluded item was left out.
Choosing the expense factor
Business account deposits are reduced by an expense ratio before they count as income. Depending on the program, that can be a standard percentage or a figure supported by a letter from your CPA or tax preparer. We run both ways and show you which one gives the stronger, defensible number.
Personal or business statements
Some borrowers qualify better on personal statements, where owner draws arrive as clean income. Others need business statements to capture the full picture. We compare the two before you send a single page to underwriting.
Large deposit sourcing
An unusually large deposit gets questioned. We flag those early and ask for the invoice, contract or sale paperwork that explains it, so the explanation is already in the file.
Reserves and down payment planning
These loans often require more months of cash reserves than a conventional loan. We count what you have in checking, savings and eligible retirement accounts and tell you plainly whether it covers the requirement.
Signs a bank statement loan fits you
Write-offs cut your qualifying income
Your business clears good money, but deductions leave your adjusted gross income too low to support the payment you can comfortably make.
A conventional lender said no on income
If a denial came down to your tax returns, not your credit or savings, deposits may tell a different story.
Your income arrives unevenly
Contractors and seasonal businesses with big months and slow months often qualify better on a 24-month average than on one year's return.
Your strongest year is not filed yet
When revenue grew fast and the latest return does not reflect it, recent statements can capture the growth sooner.
How a bank statement loan moves from first call to closing
- 1
Pre-qualification by phone
A loan officer asks how long you have been self-employed, how your business is set up, your rough monthly deposits, and your credit picture. You hear right away whether this program is worth pursuing.
- 2
Gathering statements
You send 12 or 24 consecutive months of complete statements, every page, plus proof the business exists, such as a license or CPA letter. Missing pages are the most common cause of delays, so we check the set the day it arrives.
- 3
Income calculation and file build
We calculate qualifying income, write up exclusions and large deposit explanations, and match the loan amount to that number. Then you get rate quotes on the options that work.
- 4
Underwriting, appraisal and closing
The underwriter reviews our analysis, the appraisal is ordered, and conditions are cleared as they come in. Closing is then set at a title company convenient to the property, from Manor to Round Rock.
What moves your rate and costs
Bank statement loans are priced on risk, and several parts of your file shift that risk in ways you can see. We walk through each one on your rate quotes so the numbers make sense before you commit. You get an itemized loan estimate, not a single headline rate.
- Credit score
- Higher scores reach better pricing tiers. A few points can matter, so we check whether paying down a card balance before application would help.
- Down payment size
- A larger down payment lowers the loan-to-value ratio, which often improves the rate and widens program choices.
- Statement period and expense factor
- Whether you qualify on 12 or 24 months, and which expense ratio applies, affects both the loan amount and how some lenders price the file.
- Property and occupancy
- A primary residence prices differently from a second home or investment property, and condos can carry their own requirements.
Bank statement loan questions
Something not covered here? (512) 271-4623
Should I use 12 or 24 months of statements?
It depends on your trend. If income has climbed steadily, 12 months often shows a higher average. If last year had a slow stretch, 24 months can smooth it out. We calculate both before deciding.
Do I need a letter from my CPA?
Not always, but it often helps. A CPA or tax preparer letter can confirm how long you have been self-employed and, on some programs, support a lower expense ratio than the standard one. We will tell you which version of the letter your program needs.
Is the rate higher than a conventional loan?
Usually, yes. These are non-qualified mortgages, so lenders price in the alternative documentation. If your tax returns can support a conventional or FHA loan, we will show you that pricing too so you can compare.
Can I refinance with a bank statement loan?
Yes. Self-employed borrowers use these programs for rate-and-term refinances and to pull equity out. The same deposit analysis applies, and the appraisal sets how much equity is available.
What if I mix personal and business spending in one account?
That is common, and it can still work. We separate business revenue from personal transfers and refunds, and the file explains each exclusion. Keeping the accounts separate going forward makes the next review simpler.
Find out what your deposits qualify you for
Have a rough idea of your monthly deposits and how long you have been self-employed. One conversation with a loan officer tells you whether this program fits and what to gather next.