About Manor Home Loans in Manor, TX
We are a mortgage lender that sweats the small parts of a home loan: how your income is calculated, what the appraisal says, when the rate lock expires. Those details decide whether a closing lands on schedule, so we check them at the start instead of at the end.
Why the Details Get Our Attention
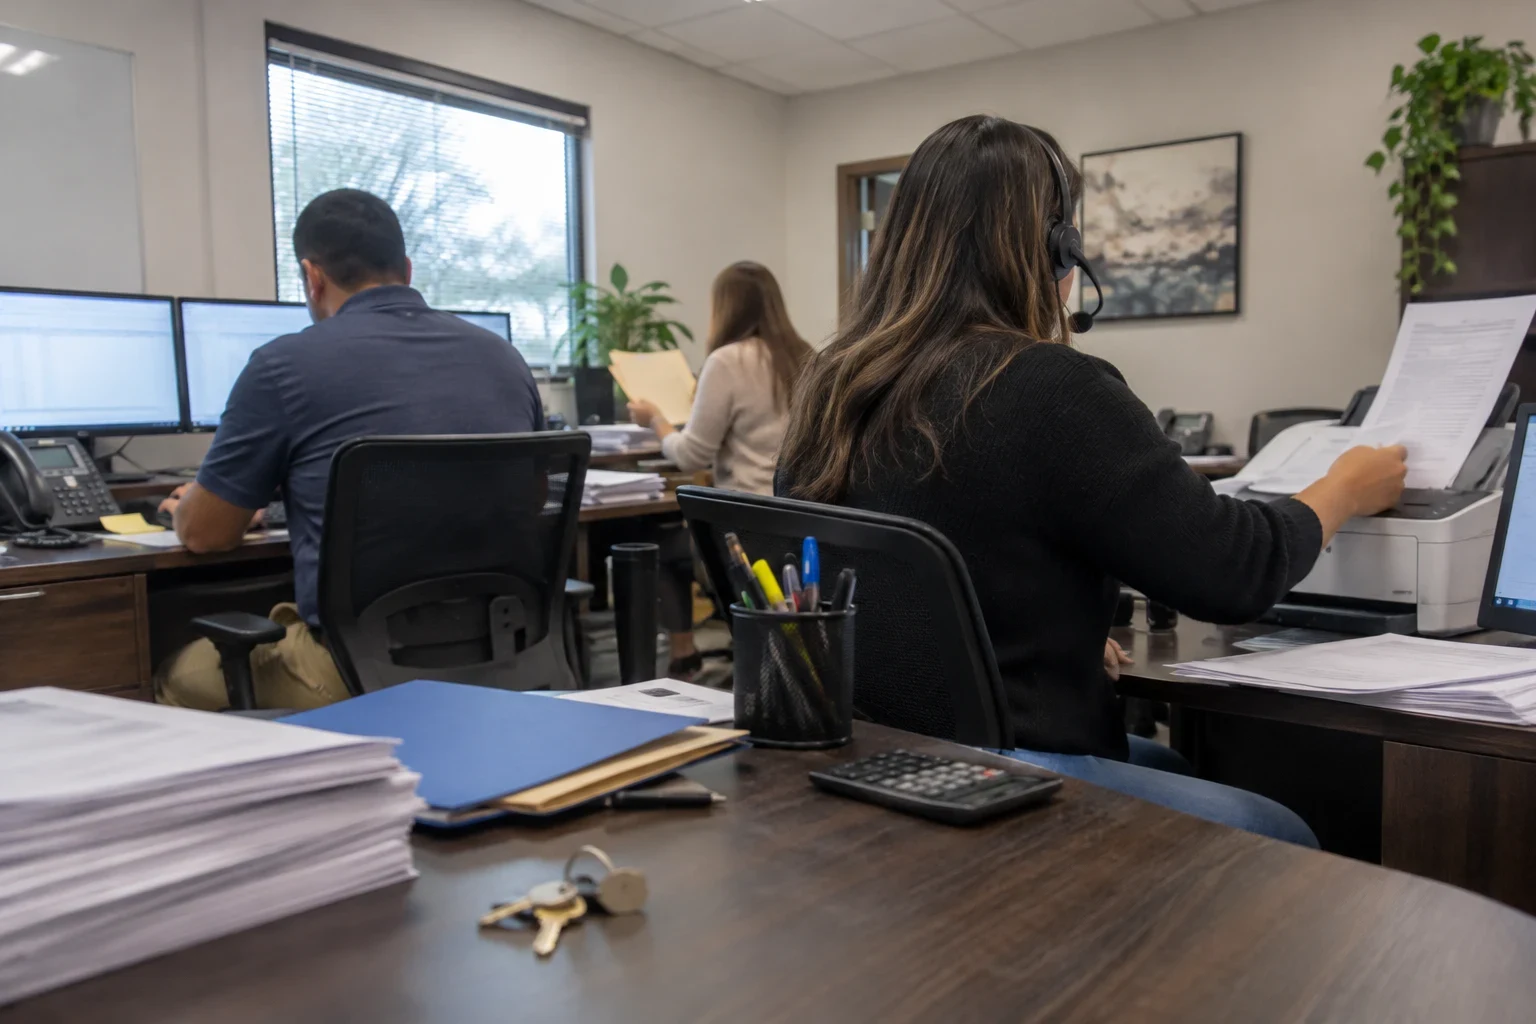
Most home loans that stall do not fail on the big questions. They stall on a pay stub missing year-to-date figures, a large deposit nobody explained, or an appraisal with a condition note about peeling paint or a missing handrail that the underwriter flags. Each one is small. Each one can push a closing back a week or more.
So we treat the loan file the way a careful builder treats framing. Before we talk rates, a loan officer reads your income documents line by line, recalculates qualifying income the way an underwriter will, and notes anything that needs a letter of explanation. Overtime, commission and self-employment income get averaged and checked for a declining trend, because that is where estimates most often run high.
The result is a pre-qualification you can lean on. When we tell a borrower what they likely qualify for, the number already accounts for debt-to-income limits, the down payment source and the reserves the loan program expects.
How We Work on Every File
Income math done twice
We calculate qualifying income from your documents, then check it against the program rules for conventional, FHA, VA or USDA financing. If the two numbers differ, you hear about it from us before an underwriter finds it.
Rate locks matched to the calendar
A lock that expires two days before closing costs money to extend. We set the lock period against the contract date, the appraisal turnaround and title work, and we tell you plainly what an extension would involve if the schedule slips.
Line-item closing figures
Your loan estimate breaks out lender fees, title charges, prepaid interest and the escrow deposit for taxes and insurance. We walk through each line so the closing disclosure holds no surprises.
The right loan, not the bigger one
Sometimes a bank statement loan fits a self-employed borrower better than a conventional file; sometimes a HELOC beats a full refinance. We explain why one structure suits your situation, including when the answer is to wait.
Where We Work
We meet borrowers at our office in Manor, or by phone and video if that suits your schedule better. Our loan officers work with buyers and owners across the surrounding area, including Pflugerville, Elgin, Hutto, Round Rock, Taylor, Hornsby Bend and Wells Branch, and we know how title companies and appraisers in this part of Texas tend to schedule.
Investors using hard money loans or bridge loans get the same file review as a first-time buyer. The documents change; the care we put into reading them does not.
- Manor
- Pflugerville
- Wells Branch
- Elgin
- Hornsby Bend
- Round Rock
- Hutto
- Brushy Creek
- Taylor
- Wyldwood
- West Lake Hills
Start With a Pre-Qualification That Holds Up
A short phone conversation with a loan officer covers your income, debts and down payment, and tells you which loan programs fit. From there we can move to a full loan application or rate quotes when you are ready.